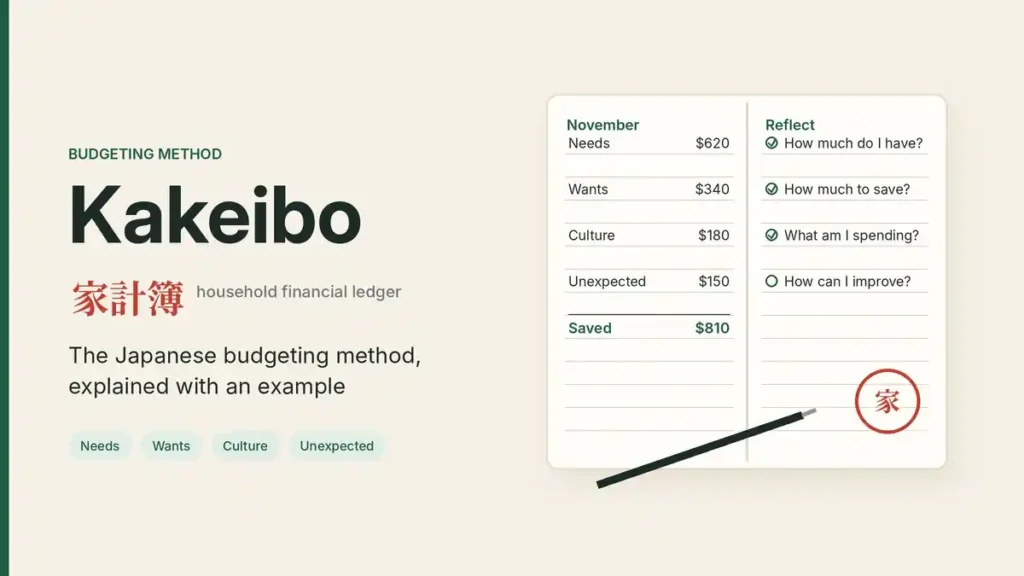
Kakeibo (pronounced kah-keh-boh) is a Japanese budgeting method built on a handwritten ledger. You set a savings goal at the start of the month, record every purchase in one of four categories, and answer four questions at the end.
The math is simple: income − fixed expenses − savings goal = what you can spend. The real point is the habit of pausing to ask why you’re buying something.
When I tried kakeibo, I was surprised by how much it helped me save and how much clearer my priorities became. Besides a notebook and a pen, it costs nothing.
What is kakeibo?
Kakeibo means “household financial ledger” in Japanese. It’s a budgeting journal: you write down your goals, track your spending by hand, and review it at the end of each month.
The process is a lot like the best budgeting apps, such as YNAB and PocketSmith, but with no downloads, bank links, or notifications. Just record-keeping.
The bigger difference is the focus on why you spend. When I can spend hundreds of dollars in a few clicks on Amazon, I appreciate a system that makes me slow down.
Where did kakeibo come from?
Japanese journalist Hani Motoko introduced kakeibo in a 1904 women’s magazine. Her readers, housewives who managed their family budgets, made it a household tradition in Japan.
It reached a wider Western audience after Fumiko Chiba’s guide, Kakeibo: The Japanese Art of Saving Money, was published in English in the late 2010s.
Chiba and others connect kakeibo to Japanese attitudes about saving. Children often receive cash as a New Year’s gift and are encouraged to hold on to it for worthwhile purchases. Japan has also long been a cash-heavy economy, though cashless payments have grown quickly in recent years.
How to do kakeibo, step by step
1. Get a ledger
Kakeibo is traditionally done by hand. A bullet journal works well, but any notebook will do.
2. Write down your monthly income and subtract fixed expenses
Fixed expenses are the bills that are the same every month: rent or mortgage, utilities, insurance, your phone plan, loan payments.
3. Set a savings goal
Choose an amount you’re confident you can save from what’s left. Subtract it, and the remainder is your spending money for the month.
4. List your four spending categories
Kakeibo sorts everything else you spend into four “pillars”:
- Needs: essentials that vary month to month, such as groceries, gas, and household supplies.
- Wants: things you enjoy but could skip, like takeout, hobbies, and clothes beyond the basics.
- Culture: books, museum tickets, concerts, classes, and streaming services.
- Unexpected: costs you didn’t plan for, like a medical bill, a car repair, or a gift.
5. Record every purchase
Write each purchase under its category with the amount.
For me, sorting was the most useful part of kakeibo. When you have to put a purchase in a category, you think about it more than you otherwise would. Separating needs from wants was harder than I expected! I also spend a lot in the culture category (I like to support the arts), and it was interesting to see on paper which creators and organizations I was choosing to support.
6. Answer four questions at the end of the month (or week)
- How much money do you have?
- How much would you like to save?
- How much are you spending?
- How can you improve?
The last question is open-ended on purpose. Improving doesn’t just mean cutting costs. It might mean spending more on what you love and less on what you didn’t value, or planning ahead so an unexpected expense doesn’t catch you off guard again.
Traditional Japanese kakeibo books included drawings of a “savings pig” fighting off an “expenses wolf” all month. You can sketch your own in your ledger, or come up with a metaphor that works for you.
Then repeat. The categories and questions stay the same every month. I liked that consistency: even when my goals changed, my process didn’t have to.
A sample kakeibo month
Here’s how one month might look for someone taking home $4,000.
- Income: $4,000
- Fixed expenses (rent, utilities, phone, insurance): −$1,900
- Savings goal: −$500
- Left to spend: $1,600
By the end of the month, the ledger looks like this:
| Category | Example purchases | Total |
|---|---|---|
| Needs | Groceries, gas, toiletries | $620 |
| Wants | Takeout, a new jacket, a video game | $340 |
| Culture | Two books, a museum visit, a streaming service | $180 |
| Unexpected | A copay and a birthday gift | $150 |
| Total spent | $1,290 |
That leaves $310 unspent, so total savings for the month come to $810 instead of the planned $500.
In the end-of-month review, the questions do the work. Maybe the takeout in Wants felt worth it, but the jacket didn’t. That’s the kind of change to carry into next month.
Kakeibo vs. other budgeting methods
- 50/30/20 budget: splits income into fixed percentages for needs, wants, and savings. Kakeibo starts from a savings goal you choose and adds a separate culture category.
- Envelope budgeting: gives each category a fixed amount up front. Kakeibo’s categories work the same way if you set limits for each, so envelope budgeters usually find it familiar.
- Budgeting apps: automate tracking by linking your accounts. Kakeibo is deliberately manual. That extra effort makes you notice your spending.
I found Kakeibo better than other systems I’ve tried at getting me to think about the reasons behind my spending. Writing each purchase by hand takes longer than tapping it into an app, and that’s the point. Handwriting may also help you remember what you wrote. If handwriting doesn’t work for you, a spreadsheet or notes app can still follow the same steps and questions.
How kakeibo helps you save
Kakeibo puts your savings goal first instead of saving whatever is left over. Like “spare change” investment apps, it helps you save a little at a time in a way you can keep up. Setting a savings goal I knew I could hit was motivating.
The monthly questions also keep longer-term goals in view, so you can plan ahead without feeling deprived now.
Who kakeibo is best for
- People who’ve struggled to stick to a budget: kakeibo’s simplicity and flexibility might do the trick.
- Reluctant or anxious budgeters: it puts you in charge and pushes back on the idea that anyone is “bad with money.”
- First-time savers: any savings goal counts, even a small one.
- Envelope budgeters: the categories will feel familiar.
Probably not ideal if you want everything automated, or you have many accounts and a complex budget to track.
Kakeibo FAQ
How do you pronounce kakeibo?
Kah-keh-boh.
Can I do kakeibo digitally?
Yes. Handwriting is traditional, but the steps and questions work in a spreadsheet or notes app. Our free budget spreadsheet is a good starting point.
Should I review weekly or monthly?
Monthly is traditional. A weekly check-in can help in your first month, while you’re building the habit.
How long should I try kakeibo?
Give it at least two or three months. The first month mostly shows where your money goes. The changes come after that.
Get started
Grab a notebook, write down this month’s income, fixed expenses, and savings goal, and start recording. If you’d rather use a spreadsheet, our free monthly budget spreadsheet for Google Sheets works with the same approach.
More For You
- When do you pay capital gains tax? Here’s what you need to know!
- Budgeting for Teens: Grow Your Money while You’re Young
- Yes, You Still Need to Know How to Fill Out a Check
- When (if ever) should you cancel a credit card?
- Online business banks compared: Novo vs Lili, Bluevine, LendingClub & Northone
- How do you know when you’re ready to buy a home?
- Best Vanguard funds
- Do not open a 529 account for your child until you’ve done this